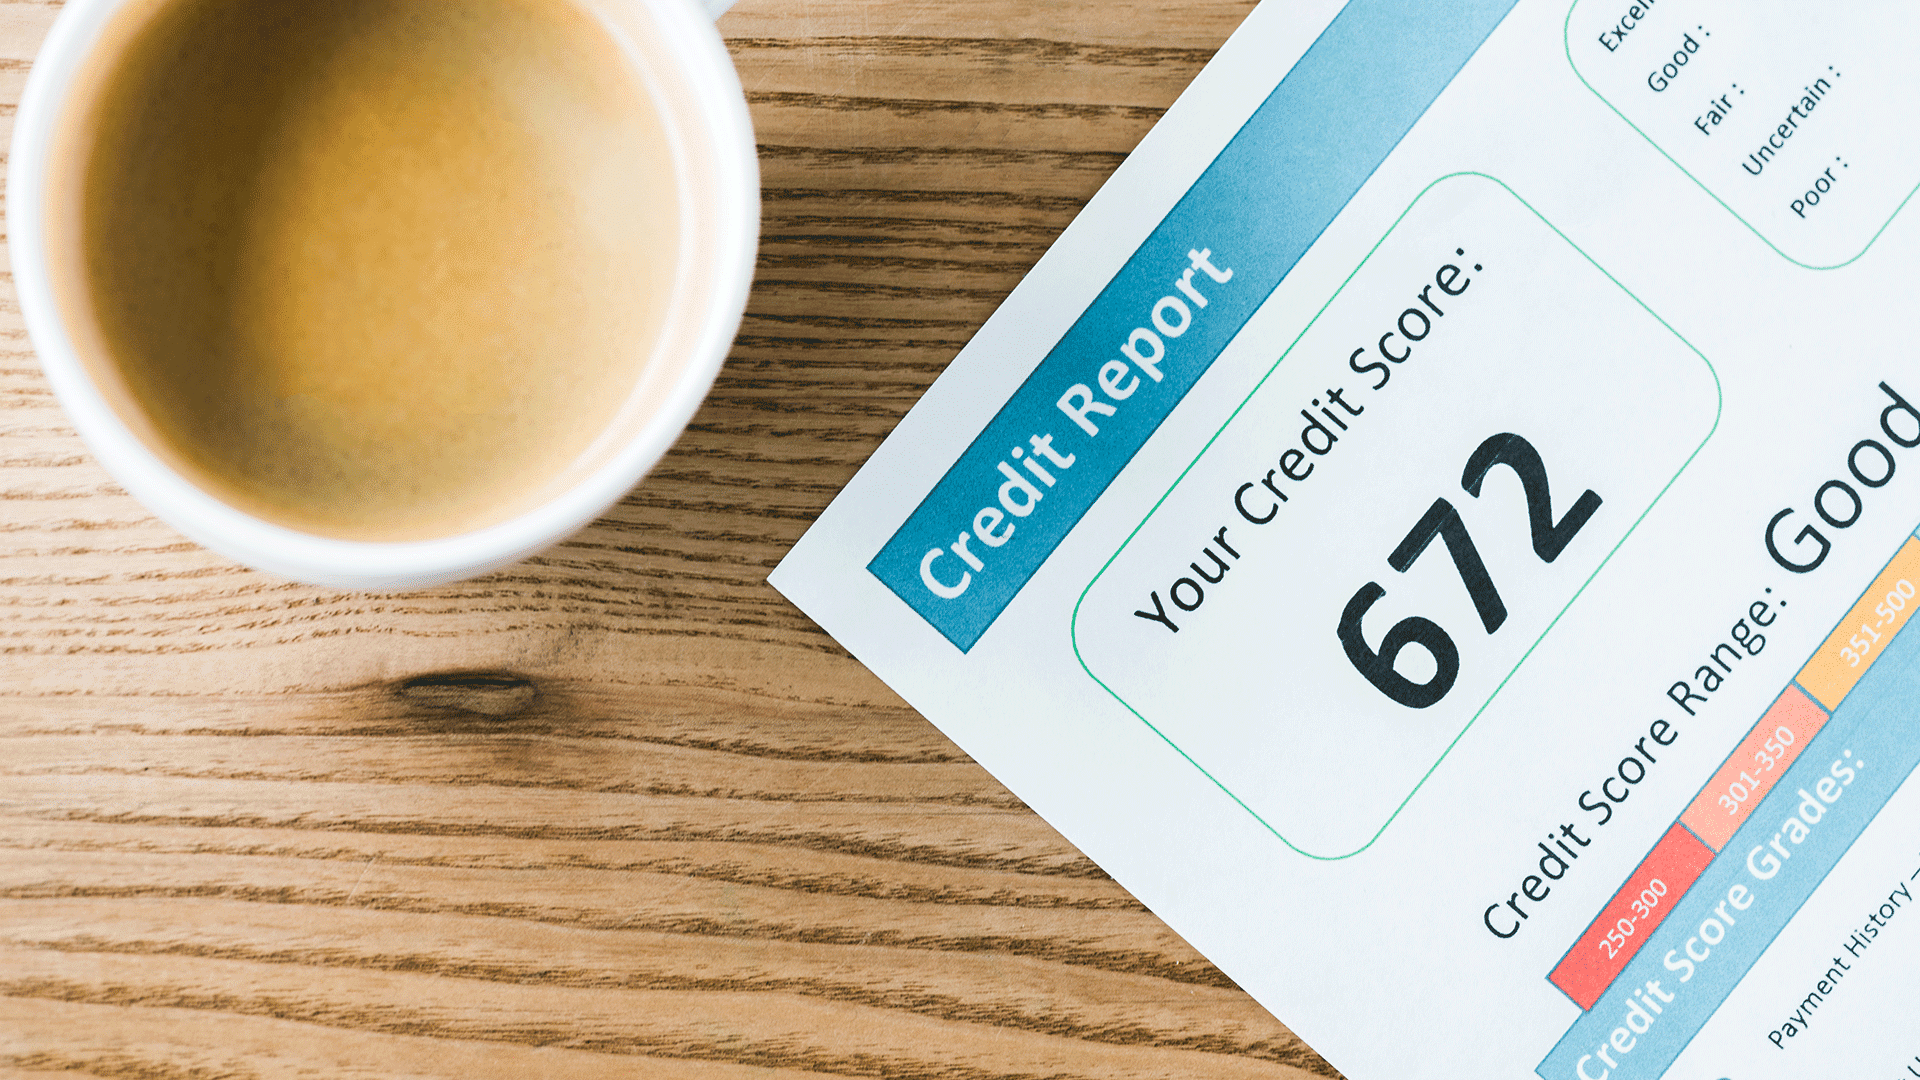
There isn’t a universal credit score you need to get a mortgage in Birmingham. Every mortgage lender has its own lending criteria, meaning the score needed to be accepted can vary depending on who you apply with.
Your credit score is just one part of your application. Lenders will also look at your income, employment, monthly commitments, deposit, and overall affordability before deciding whether to offer you a mortgage.
If you’re worried about your credit history, it doesn’t automatically mean you won’t be able to get a mortgage. Many lenders assess applications individually and may consider factors such as when any credit issues occurred, what caused them, and how you’ve managed your finances since.
Does Your Credit Score Matter When Applying for a Mortgage?
Yes, your credit score plays an important role in your mortgage application, but it isn’t the only factor lenders consider.
When you’re applying for a mortgage, lenders want to build a complete picture of your finances rather than relying on a single number.
This means someone with a lower credit score may still have suitable mortgage options if their affordability is strong, while another applicant with an excellent score could still be declined if other parts of their application don’t meet a lender’s requirements.
Is There a Minimum Credit Score Needed to Get a Mortgage?
No, there isn’t a minimum credit score that applies to every mortgage lender.
Each lender has its own approach to assessing applications. Some use credit scoring more heavily, while others place greater importance on affordability and your wider financial position.
Your credit score is simply an indication of how you’ve managed credit over time. Lenders will usually look beyond the score itself and review the information contained within your credit report.
If you’ve experienced missed payments, defaults, or a County Court Judgment (CCJ), they’ll often consider:
- What happened.
- How long ago did it occurred.
- Whether the issue has been resolved.
- How have you managed your finances since.
This means a previous credit issue doesn’t automatically prevent you from getting a mortgage, particularly if your finances have improved since then.
What Else Do Mortgage Lenders Look At?
Your credit score is only one part of your mortgage application.
Before offering a mortgage, lenders will usually assess:
- Your income.
- Your employment status.
- Your monthly committed spending.
- Existing loans and credit commitments.
- Your deposit or available equity.
- Your bank statements.
- Your affordability.
- Your overall credit history.
The aim is to establish whether the mortgage is affordable both now and in the future.
For example, someone with an average credit score but stable employment, sensible monthly spending, and a healthy deposit may have more mortgage options than someone with an excellent score but high levels of unsecured borrowing.
As a mortgage broker in Birmingham, we often find people focus on their credit score when lenders are actually considering several different parts of the application together.
What if You Have Little or No Credit History?
Having little or no credit history doesn’t automatically mean you’ll struggle to get a mortgage.
Some applicants, particularly first time buyers in Birmingham, simply haven’t borrowed much before. This means lenders have less information available rather than negative information.
In these situations, they’ll often place greater emphasis on your affordability, employment, income, and how you’ve managed your everyday finances.
A limited credit history is different from bad credit, and there may still be suitable mortgage options available depending on your circumstances.
Should You Check Your Credit Report Before Applying?
Yes. Checking your credit report before applying for a mortgage is always a good idea.
It allows you to see the information mortgage lenders are likely to review and gives you the opportunity to correct any mistakes before submitting an application.
It’s worth checking your report with Experian, Equifax, and TransUnion, as each credit reference agency uses its own scoring system and may hold slightly different information.
Don’t worry if your credit score differs between providers. This is completely normal, and many lenders focus more on the information within your credit report than the score itself.
When reviewing your report, check that:
- Your personal details are correct.
- You’re registered on the electoral roll.
- There are no accounts that don’t belong to you.
- Missed payments have been recorded accurately.
- Outstanding balances are up to date.
Correcting errors before applying could prevent unnecessary delays.
Will an Agreement in Principle Affect Your Credit Score?
Not always. Whether an agreement in principle affects your credit score depends on the lender.
Many lenders use a soft credit search when issuing an agreement in principle (also known as a Mortgage in Principle or Decision in Principle). A soft search doesn’t leave a visible mark that other lenders can see.
Some lenders carry out a hard credit search instead, while a full mortgage application will usually involve a hard search.
One hard search isn’t normally a concern. However, submitting multiple mortgage applications over a short period can affect your credit profile, which is why applying to the right lender first is often beneficial.
How Can You Improve Your Credit Score Before Applying?
Improving your credit score takes time, but there are several steps that may strengthen your mortgage application.
Making all of your payments on time is one of the most important things you can do, as lenders like to see a consistent payment history.
Reducing outstanding credit card balances may also help, particularly if you’re using a large proportion of your available credit.
Registering on the electoral roll allows lenders to verify your identity and address, while checking your credit reports regularly can help you spot mistakes before you apply.
It’s also sensible to avoid applying for multiple credit cards, loans, or finance agreements shortly before applying for a mortgage, as several hard credit searches in a short period can affect how lenders assess your application.
Making these improvements well before you apply may increase the number of lenders willing to consider your application.
Date Last Edited: July 20, 2026